6 Questions to Spot Top Workers’ Comp Insurers for Small Businesses
There is no single best carrier for every small business. The right choice depends on claims service, financial strength, and whether your state even lets you shop the private market. For high-risk operators, especially cannabis businesses and other regulated industries, a managed Employer of Record model like the one Rollwithpaid runs often beats carrier shopping outright, because service quality and classification accuracy control your costs more than any headline rate does.
TL;DR:
- Carriers with fast claims response times and comprehensive risk-control services can significantly reduce claim costs and process times, impacting long-term expenses.
- Choosing a carrier rated A or A+ by AM Best decreases the risk of insolvency and ensures claims are paid, especially during market downturns.
- Small businesses with fluctuating staffing should consider pay-as-you-go policies to prevent premium surprises and improve cash flow management.
- Larger national carriers offer benefits like multi-state coverage, specialized claims teams, and integrated payroll systems, but niche or state-specific providers may better serve high-risk or localized needs.
- A managed Employer of Record model supports ongoing classification accuracy, multi-state payroll compliance, and audit readiness, reducing risks tied to indirect costs and audit disputes.
Table of Contents
- What Workers’ Compensation Actually Covers (and Why the Carrier Matters)
- How to Evaluate and Choose the Right Workers’ Comp Insurer
- Which Carriers Dominate the Market, and What That Means for You
- State Rules That Change How You Buy Coverage
- How to Get Quotes and Compare Offers Without Surprises
- How Rollwithpaid Helps High-Risk Businesses Control Costs
- What Actually Separates a Good Decision From a Costly One
- Get Compliant Workers’ Comp Coverage Without the Guesswork
- Sources
- FAQ
What Workers’ Compensation Actually Covers (and Why the Carrier Matters)
Workers’ compensation pays medical bills and partial wage replacement when an employee gets hurt or sick because of the job. It also covers employers’ liability, the piece that protects you if an injured worker’s family sues over something the base policy doesn’t handle. Every state but Texas requires it for most employers with staff, and even Texas employers who skip it lose key legal defenses if a claim turns into a lawsuit.
The coverage itself is fairly standardized. What varies wildly is what happens after someone gets hurt, and that’s where carrier choice actually matters. A carrier with a slow claims desk lets a simple sprain drag into months of lost time and mounting reserves, which then shows up in your next renewal. A carrier that pushes nurse triage calls within hours and pairs injured workers with a return-to-work coordinator tends to close claims faster and cheaper. Industry analysis on claims service in workers’ comp points to exactly this: the client experience during a claim, not the quoted premium, is what drives long-term cost.
Three policy structures dominate the small-business market:
- Guaranteed-cost policies lock in a fixed premium based on your payroll and classification, adjusted only at renewal. This fits most small operators who want predictable budgeting.
- Loss-sensitive programs tie your final cost to actual claims experience, often with a deductible or retro-adjustment. These work for larger, financially stable employers willing to trade predictability for potential savings.
- Pay-as-you-go plans calculate premium from real payroll each cycle instead of an annual estimate, which smooths cash flow and avoids the shock of a large audit bill.
For a small business with seasonal staffing or fluctuating headcount, pay-as-you-go often removes the single biggest source of premium surprise.
How to Evaluate and Choose the Right Workers’ Comp Insurer
Picking among workers compensation insurance carriers gets easier once you stop treating it like a price comparison and start treating it like a service evaluation. Rate matters, but six other factors decide whether that rate holds steady or creeps upward every year.
Financial strength. Check the carrier’s AM Best rating before anything else. A carrier rated A or A+ has demonstrated it can pay claims through a bad underwriting cycle; a lower rating, or no rating at all, is a real risk for a business that can’t absorb a carrier insolvency mid-claim.
Claims handling and timeliness. Ask how fast a nurse or adjuster contacts an injured worker after a claim is filed. Same-day contact is the standard among carriers serious about outcomes.
Risk-control services. Strong carriers offer safety consultations, ergonomic assessments, and training resources at no extra charge. If a carrier can’t describe a specific risk-control program, that’s a gap.
Industry specialization. A carrier that underwrites your specific classification code regularly will price it more accurately and understand your claims patterns better than a generalist.
Pay-as-you-go and payroll integration. Ask whether the carrier integrates directly with your payroll system. Manual payroll reporting is where classification errors and late audits creep in.
Audit transparency. Ask exactly how the annual audit works, what documentation you need to provide, and how disputes get resolved.
Here are the questions worth asking every agent or carrier before you sign anything:
- What is your current AM Best rating, and has it changed in the last three years?
- How quickly does a nurse or adjuster make first contact after a claim is reported?
- Do you offer a dedicated claims team for my industry, or a general pool?
- Can premium be calculated through pay-as-you-go payroll reporting instead of an annual estimate?
- What does your return-to-work program look like in practice, not on paper?
- How do you handle disputed classification codes during an audit?
Vague or evasive answers to any of these are a red flag. So is a carrier that can’t produce a current AM Best rating on request, or an agent who can’t explain how audits work in plain language. You can verify complaint history yourself through your state’s insurance department or the NAIC’s complaint database, and cross-check the carrier’s market presence against NAIC’s property and casualty market share research.
Pro Tip: Ask for two claims scenarios in writing: a minor strain and a moderate lost-time injury. A carrier that gives you a vague answer for either one will likely handle your real claim the same way.
Which Carriers Dominate the Market, and What That Means for You
A handful of large carriers write most of the workers’ compensation premium in the country. AM Best’s ranking of the top 50 workers’ compensation insurers shows a market where premium concentrates heavily among the biggest writers, a pattern that has held for years. That concentration isn’t an accident. Scale lets large carriers build claims infrastructure, actuarial modeling, and risk-control teams that smaller regional players often can’t match.
For a small business, that scale translates into a few concrete advantages:
- National footprint, which matters if you operate in multiple states and want one carrier managing all your coverage.
- Larger, more specialized claims teams, often organized by injury type or industry.
- More developed risk-control offerings, including safety training platforms and ergonomic assessment tools.
- Flexible billing options, including pay-as-you-go integration with major payroll platforms.
Buyer guides tend to reflect this pattern too. Forbes Advisor’s evaluation of top workers’ compensation insurers weighs service quality, claims handling, and small-business fit more heavily than raw price, which is a useful reminder that “top workers compensation insurance” rarely means “cheapest.”
That said, bigger isn’t automatically better for your situation. Specialized carriers or state funds sometimes make more sense, particularly in three cases: your industry falls into a niche classification that a generalist carrier underprices or refuses to write, you operate in a monopolistic state where a state fund is your only option, or your business is genuinely high-risk (cannabis cultivation, roofing, waste hauling) and a carrier with deep experience in that vertical will underwrite and handle claims more accurately than a broad-market insurer guessing at your risk profile.
State Rules That Change How You Buy Coverage
Where your business operates can eliminate the private market entirely. A handful of states run monopolistic state funds, meaning employers in those states must buy workers’ compensation through the state fund rather than a private carrier. Wikipedia’s overview of U.S. workers’ compensation) lays out which states operate this way and how the rule affects purchasing.
Texas sits at the opposite extreme. It’s the one state where coverage is largely optional for private employers rather than mandatory. Skipping coverage there doesn’t mean skipping risk, though. Non-subscriber employers in Texas lose several standard legal defenses in workplace injury lawsuits, which means the decision to go without coverage should involve legal counsel, not just a cost comparison.
Before requesting quotes, confirm your state’s actual rules rather than assuming. Call your state’s department of insurance or check its website for current requirements, especially if you’re expanding into a new state or operate in a regulated industry with additional licensing overlays. When you do talk to an agent, tell them every state you have employees in, not just your headquarters state. A carrier licensed and competitive in one state may not write coverage at all in another, and finding that out after you’ve built your renewal timeline around them wastes weeks you don’t have. If your operation spans state lines, review obligations like Minnesota’s paid leave requirements alongside workers’ comp rules, since overlapping state mandates often trip up multi-state employers at the same time.
How to Get Quotes and Compare Offers Without Surprises
Getting accurate workers compensation insurance quotes starts before you ever talk to an agent. Follow these steps in order:
- Pull clean payroll data. Gather actual payroll by employee, broken out by the work each person actually performs, not just their job title.
- Verify your classification codes. Misclassified labor is the single most common reason premiums come in higher than expected. Getting classification codes right before you request quotes prevents both overpayment and audit disputes later.
- Request pay-as-you-go pricing specifically. Don’t assume it’s offered. Ask directly, and ask how it integrates with your existing payroll system.
- Ask for sample claims scenarios. Request how the carrier would handle a moderate lost-time injury, in writing.
- Compare policy endorsements line by line, not just the base premium. Two quotes with identical rates can carry very different exclusions.
Audits happen annually on most policies, and they exist to reconcile your estimated payroll against actual payroll. If your reporting has been accurate all year, the audit is a formality. If it hasn’t, you can face a retroactive bill that blows up your budget with no warning. Accurate ongoing payroll reporting is the single best defense against this.
When onboarding a new carrier, keep a simple checklist: signed application and classification worksheet, payroll reporting cadence (monthly is standard for pay-as-you-go), a named contact for audit questions, and a written return-to-work policy you can hand to supervisors.
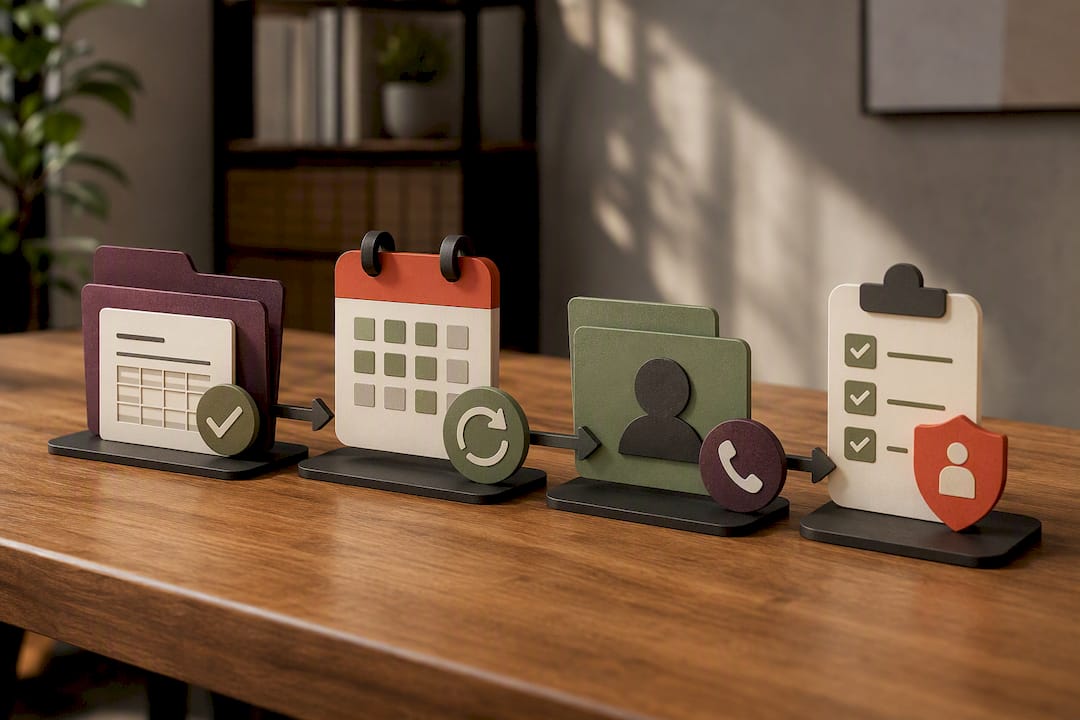
Pro Tip: Keep a running log of every classification code change and payroll correction throughout the year. It turns a stressful year-end audit into a five-minute confirmation call.
How Rollwithpaid Helps High-Risk Businesses Control Costs
Certain managed payroll and compliance services specialize in high-risk industries, including cannabis operators. That specialization matters here because classification-code accuracy and clean payroll reporting are exactly what keep workers’ comp premiums predictable. Some clients of specialized payroll providers report improved filing timeliness when classification and payroll cadence are managed as ongoing disciplines rather than annual tasks. If you want the mechanics behind correct coding, the workers’ comp classification code guide breaks down exactly where most small businesses lose money. The decision between a managed EOR route and buying direct from a carrier usually comes down to bandwidth: if you have someone in-house who lives in payroll compliance daily, direct purchasing can work; if you don’t, a managed model closes that gap.
What Actually Separates a Good Decision From a Costly One
Most small businesses over-index on the quoted rate and under-index on what happens after the first claim. That’s backwards. A carrier that’s $2,000 cheaper on paper but slow on claims handling will cost you more in lost productivity, higher experience-mod adjustments, and drawn-out disputes than the savings ever justified.
Accurate classification and clean payroll integration matter more than most owners realize until they get audited. I’ve seen the pattern repeat: a business shops three quotes, picks the lowest, then gets hit with a retroactive adjustment because payroll reporting wasn’t precise enough during the year. The cheaper quote wasn’t actually cheaper.
For high-risk operations lacking internal bandwidth to manage classification and multi-state payroll compliance, a managed service provider may reduce certain risks compared to managing coverage carrier by carrier.
— Leah
Get Compliant Workers’ Comp Coverage Without the Guesswork
A managed Employer of Record model can offer high-risk businesses ongoing support with classification accuracy, multi-state payroll, and audit readiness beyond what solo carrier shopping typically provides.
That means the items on your evaluation checklist—correct classification codes, clean payroll reporting, audit transparency—get handled as ongoing operational discipline instead of a once-a-year fire drill. For cannabis operators and other high-risk businesses, that difference shows up directly in premium stability and fewer audit disputes. If you’re ready to see how the model fits your business, start with Rollwithpaid’s Employer of Record overview or check current pricing to see what a managed approach costs against what you’re paying now.
Sources
- Best’s Rankings Top 50 Workers’ Compensation Insurers
- NAIC property & casualty market share research
- Best Workers’ Compensation Insurance — Forbes Advisor
FAQ
Who Has the Best Workers Comp Insurance?
No single carrier is best for every business; the right fit depends on your state, industry classification, and how much you value claims service over headline price. For high-risk small businesses, a managed approach through an Employer of Record like Rollwithpaid often delivers more predictable costs than shopping carriers directly.
What Are the Top Workers’ Compensation Insurance Companies?
Market concentration is heavy at the top: a handful of large national carriers account for most premium written, according to AM Best’s rankings. Buyer guides like Forbes Advisor evaluate these large writers alongside specialized carriers based on service and small-business fit, not just size.
Who Are the Big Five Insurers?
There’s no single official “big five” list; market share shifts by state and industry, and rankings vary depending on whether you measure by direct premium written or overall market presence. The AM Best top 50 ranking is the most reliable reference for current standing.
How Much Should I Pay for Workers Comp Insurance?
Premiums are calculated from your payroll, classification codes, and state rates, so there’s no flat number that applies across businesses. Pay-as-you-go pricing tied to accurate payroll reporting is generally the most reliable way to avoid overpaying or facing a surprise audit bill.
Is a Managed Payroll Provider a Substitute for Buying Workers’ Comp Directly?
A managed Employer of Record service like Rollwithpaid doesn’t replace the insurance requirement, but it does handle the payroll accuracy and classification work that keeps your premiums stable and audits clean. For high-risk industries especially, that operational layer often does more to control long-term cost than switching carriers.
Recommended
- Minnesota Paid Leave: Employer Obligations After Launch
- Understanding Employer of Record for High-Risk Industries
Roll With Paid. is not a law firm and does not provide legal advice. This article summarizes Minnesota law as of August 2026 and is general information only. Tip arrangements are fact-specific; before changing a policy, consult employment counsel or contact DLI Labor Standards at 651-284-5075.